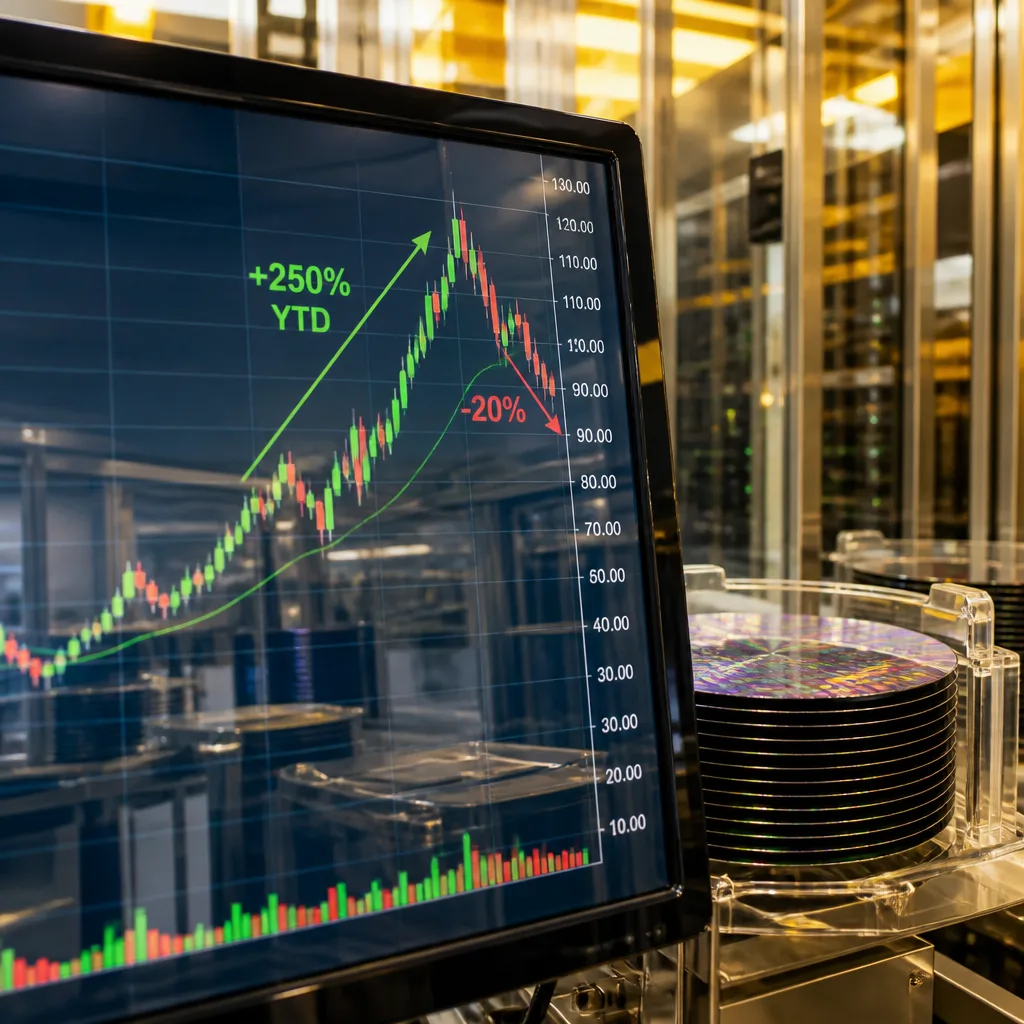
Micron Technology shares have climbed sharply in 2026 — up about 250% year-to-date — but the stock has also retreated roughly 20% from recent all-time highs, prompting fresh debate among investors over whether the run can continue or if a larger correction is coming.
What's driving the rally
Micron makes the two primary types of semiconductor memory: DRAM (fast, volatile memory used alongside processors) and NAND (non-volatile storage used for long-term data). Those chips power nearly every modern computing device and are critical components inside data centers. A pronounced wave of demand from cloud and enterprise customers has pushed chip prices higher as the fabrication supply chain strains to keep up.
Capacity timing and market balance
The company and industry peers are racing to add production, but they face a dual risk: the immediate shortage is boosting prices and profits, yet the demand surge may be temporary. Micron expects some new capacity to come online around mid-2027, while the firm anticipates that broader market conditions may not improve until 2028 or later. That timeline matters for investors trying to judge whether current valuations reflect sustainable earnings or a cyclical peak.
Valuation snapshot
Despite the steep 2026 gain, trading multiples cited for Micron remain moderate by technology-sector standards. The stock is shown at about 13.5 times forward earnings and roughly 6.6 times next year’s earnings in the provided figures, suggesting the market is pricing in ongoing growth but still treating the business as cyclical.
- YTD performance: ≈ 250% gain
- Pullback from highs: ≈ 20%
- Expected capacity online: mid-2027
- Market improvement forecast: 2028 or later
| Metric | Value |
|---|---|
| Current price | $981.25 |
| Today’s change | -1.05% (−$10.39) |
| Forward P/E | 13.5x |
| Next-year P/E | 6.6x |
For investors, the central question is whether Micron’s recent gains reflect a durable expansion of demand that will outlast the current tightness in supply, or a cyclical peak that could reverse once new factories start producing. Management’s conservative approach to capacity expansion — mindful of not overbuilding for a demand wave that could wane after a few years — is a key variable.
The outlook leaves room for both opportunity and risk. If memory shortages and elevated prices persist into 2027 and beyond, the company may sustain higher profits until new plants come online. Conversely, rapid capacity additions industry-wide in response to elevated margins could soften pricing and earnings when that new supply arrives.
Investors weighing Micron now must balance the company’s central role in the memory market and its apparent growth runway against the inherent cyclicality of semiconductor manufacturing and the timing of capacity increases. Those dynamics will determine whether the current pullback represents a buying window or the leading edge of a larger correction.