Artificial intelligence is moving from an experimental tool to a core part of mortgage operations, forcing lenders to rethink how they collect, govern and act on data across the lending lifecycle. In a discussion with HousingWire, Chris McEntee, vice president of corporate and product development at ICE, laid out how AI is changing business intelligence in mortgage and why organizations must design systems that can scale responsibly.
From dashboards to automated alerts
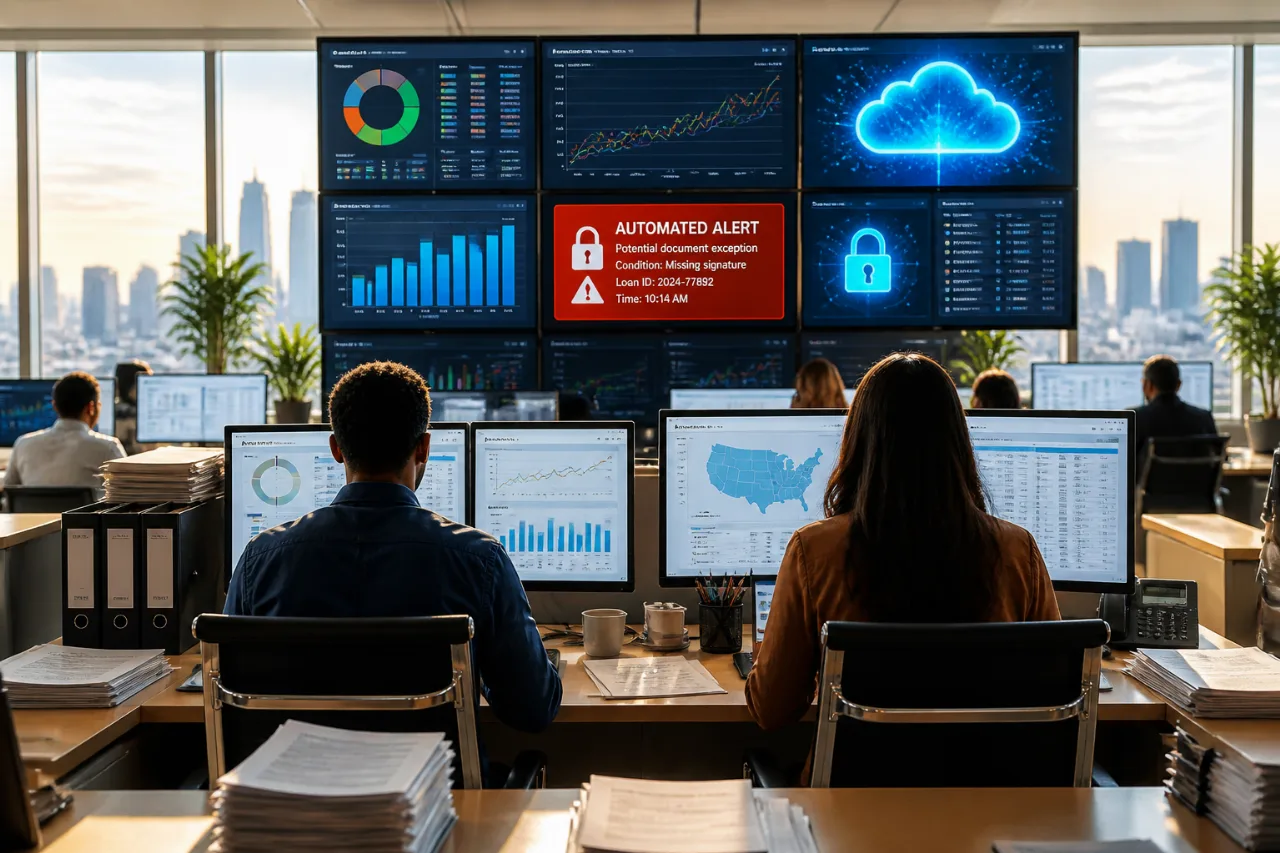
Historically, business intelligence in lending emphasized gathering and cleaning data and presenting it through dashboards to guide decisions. That model still matters, but AI changes the downstream requirements: lenders increasingly expect systems to automatically detect emerging trends and notify stakeholders in real time so operations can respond immediately.
"Business intelligence is undergoing a major transformation because of AI," McEntee said.
The shift moves BI from a retrospective reporting function toward a proactive, operational layer that triggers actions — such as marketing outreach, pricing adjustments or workflow automation — based on AI signals.
Variation by business model and scale
McEntee emphasized that lenders differ widely in how they consume and apply data. Some institutions harness data to:
- Automate marketing campaigns and target refinance or purchase opportunities in near real time;
- Integrate enterprise data with proprietary market feeds and third‑party sources to sharpen decisioning;
- Prioritize simple visibility into pipeline performance rather than complex real-time environments.
That range means AI adoption will look different at a community lender than at a large mortgage bank with an enterprise data science team running sophisticated real‑time environments.
Data governance as a gating factor
Across use cases one consistent priority emerges: accurate data and strong governance. McEntee warned that automated processes are only as reliable as the data they depend on. Organizations need a clear source of truth and must ensure third‑party inputs don’t introduce conflicting signals that could undermine automated decisioning.
| Traditional BI | AI-driven BI |
|---|---|
| Collect, clean, visualize | Real‑time detection + automated actions |
| Periodic reporting | Continuous monitoring and alerts |
| Human-led interpretation | Machine-assisted operational triggers |
McEntee described ICE’s approach as collaborative: the company works with clients to mix their own enterprise data with ICE’s market information and other third‑party sources to deliver usable solutions. Many clients seek examples from peers to guide their own implementations.
Implications for households and mortgage markets
For borrowers and households, the shift toward AI‑enabled mortgage BI could mean faster responses on refinance and purchase opportunities and more tailored outreach from lenders. For businesses, the change raises operational priorities: investments in data architecture, governance frameworks and talent capable of supervising AI‑driven workflows.
The underlying message from industry practitioners is clear: lenders must build a dependable data foundation before automating critical functions. Without that, AI may accelerate activity — but also amplify errors.
As AI becomes embedded across origination, pricing and portfolio management, the mortgage industry’s competitive landscape will increasingly favor organizations that combine clean, governed data with disciplined automation strategies.